What is Carpet Area on a Loan Against Property?
Dasadia Editorial Team · Updated August 2026
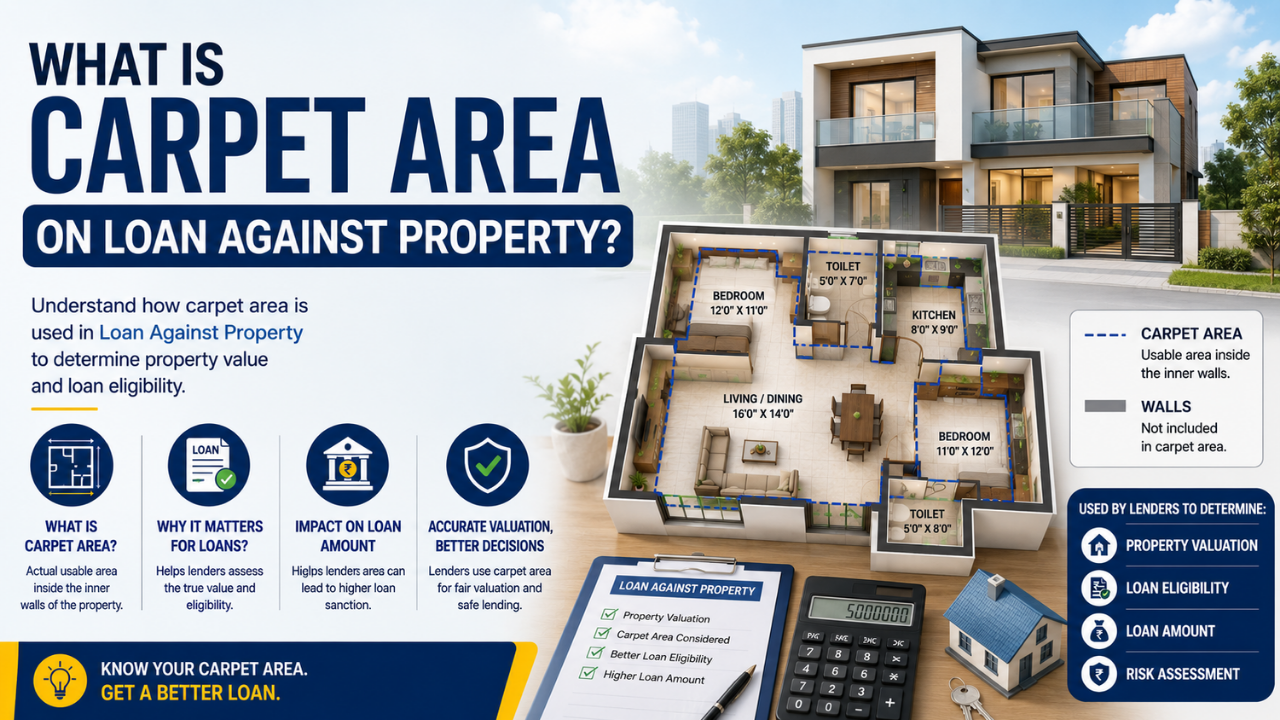
On a loan against property, carpet area is the usable floor space inside your walls that the lender’s empanelled valuer measures on site. It is the area figure your valuation is built on, and through that valuation it sets the ceiling on what you can borrow.
- Carpet area on a LAP is measured, not quoted. The valuer's on-site figure governs even where your own documents say something else.
- Two flats of identical advertised size can carry very different carpet areas, and that difference flows straight into the sanctioned amount.
- A LAP is usually secured on an older property with no RERA carpet figure, so three of your documents may state three different areas.
- Anything built or enclosed without approval is excluded from the area the lender values.
Most borrowers discover this on the day the valuer visits.
The distinction matters more here than on a home loan, and the reason is plain arithmetic on old buildings. When you buy a new flat, RERA fixes the carpet area, MahaRERA publishes it and the sale agreement states it. When you mortgage a flat you have owned for twenty years, none of that exists. The agreement may predate 2017 and state built-up or saleable area. The society’s records may still carry the builder’s original marketing figure. The municipal tax assessment may use a third number altogether. The valuer settles the disagreement by measuring, and whatever he writes down is what the bank lends against.
Key takeaways
- Lenders value residential property on carpet area because it reflects the functional space, not the loading a builder attributed decades ago.
- On identical 1,200 sq ft flats, one with 1,000 sq ft carpet and one with 850, the larger carpet area produces the higher valuation and the larger loan.
- Five documents can state an area for the same flat. The valuer's measurement, checked against the sanctioned plan, is the one that counts.
- Unauthorised construction and deviations from the approved plan are excluded from the valuation, and a serious deviation can stop the file.
- Self-occupied residential property attracts the highest LAP LTV, commonly up to about 75%. Commercial property is often funded at 50% to 60%, and plots lower still.
- LAP interest rates ran roughly 8.5% to 14% a year through 2026, with tenures extending to 20 or 25 years.
- Final eligibility including valuation typically takes seven to ten working days.
- If values in your area fall after disbursal, the lender can ask for additional collateral or a part prepayment to restore the LTV.
Where the carpet area figure comes from in a LAP
Five documents can carry an area for the same flat, and on older Mumbai property it’s common for them to disagree with each other.
The last row decides your loan. Everything above it is corroboration the valuer checks against, and the sanctioned plan is the reference he holds all of it up to. Where your deed says 1,150 square feet and the tape says 980, the tape wins. We could not find a lender that treats a document figure as overriding a physical measurement, and it would be strange if one did, because verifying the documents is the entire purpose of the site visit.
In Mumbai those papers sit in four different places. The deed is with you or the sub-registrar, the मिळकत पत्रिका is with the city survey office, the share certificate is with your society secretary, and the assessment is with your BMC ward office. Collecting all four takes about a week, which is a week you have before the valuer arrives rather than after.
Pull these five together before you apply rather than after. If they already agree, your valuation is a formality. If they don’t, you now know what the valuer is going to find, which is a far better position than learning it from a sanction letter that came in ₹40 lakh short.
Why the same square footage produces two different loans
Here’s the arithmetic that makes carpet area worth arguing about.
Take two flats in the same Andheri East building, both sold as 1,200 square feet. One was laid out with a 20% loading factor and carries 1,000 square feet of carpet. The other sits on a corner with more circulation space attributed to it and carries 850. At a valuer’s carpet rate of ₹42,000 per square foot, the first values at ₹4.2 crore and the second at ₹3.57 crore. On a 60% loan against property that is ₹2.52 crore against ₹2.14 crore. Same advertised size, same address, same building, and ₹38 lakh of difference in what you can raise against it.
None of that gap is negotiable. It was fixed when the building was designed.
Mumbai loading factors commonly run 30% to 40%, and in some towers higher, so the spread between two flats marketed at the same size can be wider than this example. This is also why comparing your flat’s value to a neighbour’s recent sale is unreliable unless you know both carpet areas.
What gets deducted from the area
The valuer doesn’t count everything he measures. Area built or enclosed without approval comes out of the figure. An enclosed balcony, a covered terrace, a mezzanine added later, a flat merged with the one next door without a sanctioned amalgamation, each of these gets deducted from the area used for valuation, and a serious deviation can stop the application rather than merely shrink it. Older Mumbai stock is full of these because they were ordinary practice for decades. That your neighbour did the same thing is not a defence a valuer is able to accept.
If your flat has an enclosed balcony, expect it to be excluded. Budget on that assumption rather than hoping.
Location can also disqualify a property outright rather than reduce it. Lenders maintain internal negative lists covering unauthorised colonies and high-risk zones, and no amount of carpet area helps if the address sits on one. Worth establishing early, before you pay a valuation fee.
Carpet area sets the valuation, property type sets the multiplier
Measuring the flat gives you a value. What fraction of that value you can borrow is a separate question, and the spread across property types is wide.
Commercial LAP is where borrowers are most often caught out. A shop with a strong rental record still tends to fund at 50% to 60% rather than 75%, because the lender is thinking about how long it would take to sell if things went wrong. Carpet area is measured the same way on a shop as on a flat. What changes is the multiplier applied to it.
One more thing that surprises people. All co-owners of the property have to be co-applicants, so a flat held jointly with a sibling or a parent cannot be mortgaged on one signature.
If the measured area comes in lower than your documents
You have three options and one of them is worse than it looks. You can accept the lower sanction and scale back whatever you were planning to fund. You can regularise the deviation with the municipal authority where that’s possible, then ask for a revaluation, which takes time but fixes the figure permanently. Or you can take the file to a different lender.
Shopping the file is the option to be careful with. Valuers work from the same comparable transactions and the same sanctioned plan, so a second opinion usually lands close to the first. Each application also leaves a credit enquiry on your record. Our view is that two lenders is a reasonable test and five is a self-inflicted wound.
Regularise first if you can. It’s the only route that raises the number permanently.
Remember that the valuation is not permanent in the other direction either. If capital values in your area fall after disbursal, the lender is entitled to ask for additional collateral or a part prepayment to bring the LTV back within limits. That happened in several commercial markets between 2020 and 2021, and it is a real risk to price into any LAP taken at the top of the permitted ratio.
Before you apply
Do this first
- Pull the sale deed, property card, society records and municipal assessment and compare the area on each.
- Get a copy of the sanctioned plan from the society or the corporation and check your layout against it.
- Measure the flat yourself, room by room, so you know roughly what the valuer will find.
- Confirm every co-owner is willing to be a co-applicant before you start.
- Ask the lender for an indicative view on the building, which many will give informally.
- Ask for a copy of the valuation report. You are paying for it.
Mistakes that shrink the sanction
- Assuming the saleable area on your original brochure is what the bank will value.
- Treating an enclosed balcony or covered terrace as part of your usable area.
- Applying to five lenders in succession after one low valuation.
- Borrowing at the maximum permitted LTV with no headroom if values soften.
- Overlooking that interest on a LAP is deductible only where the funds go into a business.
The single most useful hour you can spend is with a tape measure and the sanctioned plan, before anyone from the bank arrives. It costs nothing and it removes every surprise the process is capable of producing.
Frequently asked questions
It is the usable floor space inside the walls of your property, measured on site by the lender’s valuer. That measurement drives the valuation, and the valuation sets the maximum you can borrow.
Carpet area is the primary basis, because it reflects functional usable space rather than the loading a builder attributed. The valuer records built-up area as well and checks both against the sanctioned plan.
From its own measurement. The sale deed, property card, society records and municipal tax assessment are all checked, but where they disagree, the valuer’s physical measurement against the sanctioned plan governs.
That is common on pre-2017 documents, which often state built-up or saleable area instead. It does not block the loan. The valuer measures the flat and works from that figure.
The lower figure is used, so your valuation and your sanction both fall. You can accept it, regularise any deviation and seek a revaluation, or approach another lender, though a second valuer usually reaches a similar number.
Yes, other things being equal. On two 1,200 sq ft flats, one with 1,000 sq ft carpet and one with 850, the first values higher and supports a larger loan. The rate per square foot for the locality matters just as much.
Generally not, if the enclosure was done without approval. Unauthorised construction and deviations from the sanctioned plan are excluded from the valuation, and a significant deviation can cause rejection.
Commonly up to about 75% of assessed value for self-occupied residential property. Let-out residential tends to be similar or lower, commercial property often 50% to 60%, and vacant plots lower still with a shorter tenure.
Because the resale market is thinner and disposal takes longer. The lender is assessing how quickly the asset could be sold if the loan went bad, and prices that risk into the ratio rather than the valuation.
Yes. Lenders accept let-out residential property, but they weigh the lease period and the tenant’s stability, and the ratio offered may be lower than on a self-occupied flat.
Usually yes, if the plot sits within municipal limits and is clearly demarcated. Expect a lower LTV and a shorter tenure, often around 10 to 12 years.
Final eligibility including the property valuation typically runs seven to ten working days. An initial indicative check is much faster.
The borrower. The lender appoints a valuer from its own panel and passes the cost on. Ask for a copy of the report, since you have paid for it and it is the only independent measurement of your property you will be given.
Yes. If capital values in your area decline and the loan to value ratio moves outside limits, the lender can seek additional collateral or a part prepayment. Borrowing at the maximum permitted ratio leaves no cushion for that.
Only where the borrowed funds are used for business purposes, in which case the interest can be treated as a business expense. A LAP taken for personal use does not carry the deductions available on a home loan.
Verified key facts
- Lenders focus on carpet area rather than built-up area when valuing residential property, because it reflects functional usable space.
- On two apartments of 1,200 sq ft, one with 1,000 sq ft carpet and one with 850 sq ft, the larger carpet area receives the higher valuation.
- Unauthorised floors and deviations from the approved plan are excluded from a lender's valuation.
- The technical appraisal measures carpet and built-up area and checks both against the sanctioned plan.
- Self-occupied residential property attracts the highest LAP loan to value, commonly up to about 75%.
- Commercial property is frequently funded at a lower ratio, around 50% to 60%.
- Vacant residential plots are eligible if within municipal limits and demarcated, typically at a lower LTV and a tenure of about 10 to 12 years.
- All co-owners of the mortgaged property must be co-applicants on the loan.
- LAP interest rates in India ran broadly 8.5% to 14% a year as of April 2026, with tenures extending to 20 or 25 years.
- Final LAP eligibility including valuation typically takes seven to ten working days.
- Where property values decline after disbursal, lenders may seek additional collateral or part prepayment to restore the loan to value ratio.
- Interest on a LAP is deductible only where the funds are applied to business purposes.
- For regulatory and lending purposes valuers must be registered with the IBBI, and reports are typically valid six to twelve months.
Sources and references
- RBI – Reserve Bank of India
- IGR Maharashtra – Department of Registration and Stamps
- MahaRERA – Maharashtra Real Estate Regulatory Authority
- IBBI – registered valuers
- MCGM – Brihanmumbai Municipal Corporation, property tax assessment
- Electronica Finance – how carpet area affects a loan against property valuation
- Stashfin – loan against property versus home loan, collateral and LTV
- Creditcares – loan against property eligibility 2026
- Dealplexus – loan against property in India, pricing and revaluation risk
- Ambak – carpet area versus built-up area and lender valuation
- Kotak – how banks evaluate property before sanctioning a loan
- ICICI Bank – RBI guidelines for home loans and loan against property
Disclaimer: This page explains how lenders treat area when valuing property offered as security for a loan against property. It is general information rather than financial or legal advice, and we are neither a lender nor a registered valuer. Loan to value ratios, interest rate ranges, tenures and eligibility rules are stated as they applied during 2026, and every lender applies its own credit policy within the regulatory limits, so the amount any particular institution sanctions may differ from the illustration here. The two-flat comparison uses assumed figures to show how the arithmetic behaves and is not a valuation of any property. Verify your own area records with the corporation and the registration department, have the sanctioned plan checked by a qualified professional, and discuss your eligibility with your lender before acting.
Buying rather than borrowing?
153 East by Dasadia Developers LLP is a freehold residential development in J.B. Nagar, Andheri East, with 1 to 4 BHK configurations close to the Aqua Line at Marol Naka, the Western Express Highway and both airport terminals. MahaRERA registration no. PR1180002502968, with carpet areas published and verifiable on the MahaRERA portal. Ask us for the configuration sheet with RERA carpet areas and indicative pricing, or book a site visit. Pricing is indicative and subject to change.